
Buying a home in Fort Walton Beach or anywhere on the Emerald Coast starts with the right area and an honest look at the costs before you write an offer. We are Derrick and Emily Sumner, and this is our plain guide to choosing among the seven areas we serve, financing, Florida taxes and insurance, condo rules and the steps from offer to keys.
Choosing among the seven areas we serve
Most buyers narrow the map by commute first. Fort Walton Beach is our home base, with older neighborhoods near the Santa Rosa Sound and short runs to both Eglin and Hurlburt. Navarre, west across the county line in Santa Rosa County, has more newer construction and the causeway to Navarre Beach. Niceville and Valparaiso sit near Eglin's East Gate on the other side of the base.
The Hurlburt Field area takes in Mary Esther, Fort Walton Beach and Navarre around the gate on US-98, while the Eglin AFB area runs from Fort Walton Beach and Shalimar up Eglin Parkway toward Niceville and Valparaiso. Crestview, inland on I-10, is where many buyers look for more house and land for the money, with an easy run to Duke Field. Pensacola offers downtown living and bigger-city amenities near NAS Pensacola and Whiting Field. Each area has its own page on our site, and we are glad to compare them for your commute, budget and the school zones you care about.
Pre-approval and talking to a lender
You do not need a pre-approval for a first call with us, but you will want one before we tour seriously. A lender reviews your credit, income, debts and savings and gives you a number to shop with, and a pre-approval letter makes your offer stronger. Homes we list go under contract in 17 days on average, so being ready to move matters on this coast.
Talk to more than one lender and ask each for a written Loan Estimate so you can compare. If you are VA-eligible, request your Certificate of Eligibility early, since eligible buyers can often purchase with no down payment and no monthly mortgage insurance. FHA and conventional loans have their own down payment minimums, and your lender can explain which fits your situation.
The real costs of buying a home in Florida
Plan for closing costs on top of your down payment. They usually include lender fees, title insurance, recording fees and prepaid taxes and insurance. Florida also charges documentary stamp tax on deeds, notes and recorded mortgages, at 70 cents per $100 on deeds outside Miami-Dade County, and your contract spells out who pays which costs.
Once you own the home and make it your permanent residence by January 1, you can apply for Florida's homestead exemption with the county property appraiser, generally by March 1. It can reduce the home's taxable value by as much as $50,000, with part of that amount now adjusted for inflation, and it qualifies the home for the Save Our Homes cap on assessment increases.
Insurance deserves attention early. Homeowners policies do not cover flood, so flood coverage is a separate policy, and new flood policies generally carry a 30-day waiting period. A four-point inspection checks the roof, electrical, plumbing and heating and cooling systems, and Citizens Property Insurance, for example, requires one for homes more than 20 years old. A wind mitigation inspection records features such as roof attachment, roof-to-wall connections and opening protection on the state's uniform form, which stays valid for up to five years if nothing material changes. Florida law requires insurers to offer discounts or credits for qualifying wind features, so that report can lower your premium.
HOAs, condos and Florida's condo safety rules
Many subdivisions here have homeowners associations, so read the covenants, dues and rental rules before you commit, especially if you might rent the home out at your next move. Condos deserve a closer look. Under Florida law, condo buildings three habitable stories or taller need a milestone structural inspection by the end of the year they turn 30 and every 10 years after, and local officials can move that to 25 years for buildings near salt water.
The same buildings need a structural integrity reserve study at least every 10 years, covering items such as the roof, structure, plumbing, electrical systems, waterproofing and windows. Before your review period ends, ask for the latest inspection report, the reserve study, the current budget and any planned special assessments, and we will help you read them.
Touring, making an offer and closing
You can tour in person with us, or on video if you are still out of state. We film the rooms, the street and the yard, and we tell you what a camera hides. When the right house turns up, we pull recent nearby sales so you know what it is worth, then write and negotiate the offer with you.
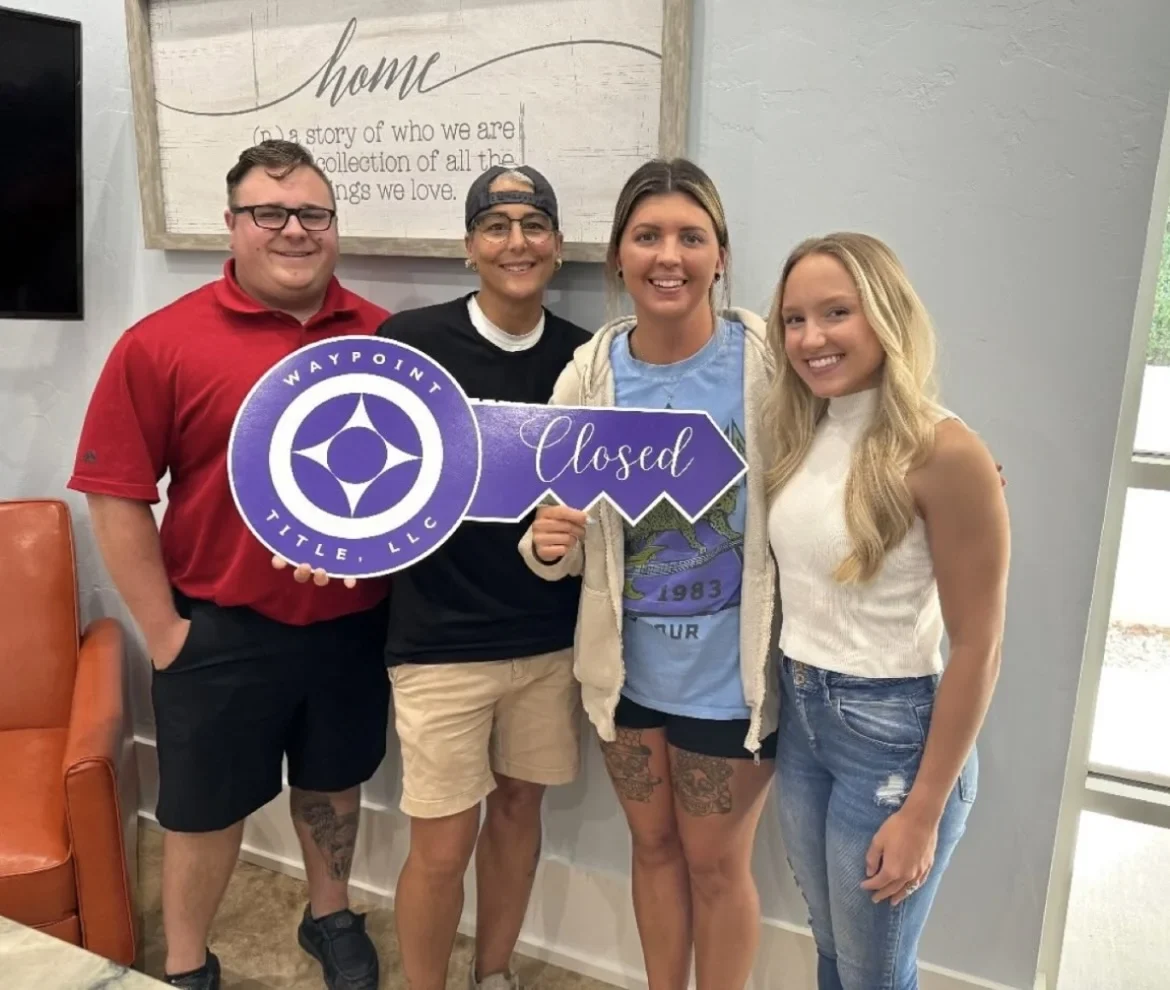
After your offer is accepted, you place your escrow deposit, schedule inspections, gather insurance quotes and work through the lender's appraisal and underwriting. We keep those dates on a written plan and negotiate repairs or credits if the inspection turns something up. At closing you sign, the funds move and the keys are yours. Buying from out of state follows the same steps, with more of it handled by phone, video and electronic signature, and your title company will confirm what needs a notary.
Working with Sumner Realty
If you are relocating on military orders, our PCS relocation guide covers VA loans, BAH and buying from out of state. Already own a home here? See how we approach selling your home.
We are a husband-and-wife team, and one of us is on every call. We have sold more than $16 million in homes on this coast, and we would rather tell you a house is wrong than watch you buy it. Tell us your timeline and the areas you are weighing in the form below, or Call/Text 360-229-3252, and we will tell you what is realistic.